Compelling Valuations in Japan
Japanese equities are currently trading at compelling valuation levels compared to other developed equity markets around the world and relative to their own historical averages. We believe the Japanese market deserves a closer look.
-
 Masakazu Takeda, CFA, CMAPortfolio Manager
-
 Angus Lee, CFAPortfolio Manager
-
 Tadahiro Fujimura, CFA, CMAPortfolio Manager
-
 Takenari Okumura, CMAPortfolio Manager
1. Attractive Price-to-Earnings Multiple
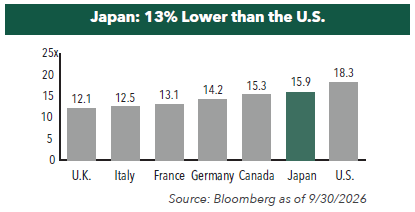
The price-to-earnings multiple, or P/E ratio, is the most common measure used to value equities. Japanese large cap equities, as represented by the Tokyo Price Index (TOPIX), are currently trading on a P/E multiple of 15.9x 2026 forward earnings, 13% lower than the U.S.
2. Low Price-to-Book
On a price-to-book basis (P/B), Japanese equities are also offering investors great value compared with other global developed equity markets. TOPIX is trading at just 1.8x book value, about a third lower than the average among the top developed equity markets and more than two thirds lower than the U.S.
_1793306751.png)
3. Japan Small-Caps at a Discount
Small-cap Japanese companies are also trading at a discount to international peers. Small-cap stocks in Japan are trading on just 13.6x 2026 forward earnings, and as a point of reference, a 40% discount to U.S. small caps trading at 22.5x.
_1793306770.png)
4. Japan’s Attractive P/E Relative to History
_1793306835.png)
Summary
We believe Japan’s growth story is just starting to unfold. Following the advent of Abenomics, many Japanese companies are experiencing higher profitability due to corporate restructuring, better governance, and a more competitive currency. With Japanese equities currently offering attractive valuations compared to G7 developed country equity markets and relative to history, we believe Japan deserves a closer look as a component of an investor’s portfolio.
1. Active, “Feet on the Street” Management
Both Funds are sub-advised by Tokyo-based SPARX Asset Management. One of the largest and most experienced independent Asia-based asset management specialists, SPARX conducts over 2,000 meetings with companies in Japan and throughout Asia each year.
2. Consistently Strong Performance
The Japan Fund (HJPIX) achieved top 32% performance for the 1, 3, and 10 year period and the Japan Small Cap Fund (HJSIX) achieved top 21% performance for the 10 year period in the Morningstar Japan Stock Funds category ended September 30, 2026.
3. Impressive Excess Return
Over the past 3 years, the Funds provided risk-adjusted excess return relative to the Japanese markets, with the Japan Fund (HJPIX) delivering an alpha of 4.74 relative to the Russell/Nomura Total MarketTM Index and the Japan Small Cap Fund (HJSIX) delivering an alpha of 2.23 relative to the Russell/Nomura Small CapTM Index.
_1793306902.png)
*Based on total returns. **The Overall Morningstar Rating is based on risk adjusted returns. 1Represents the performance of the Institutional Class shares after June 15, 2015 (inception of the share class) and Investor Class for periods prior to that date.
Performance data quoted represents past performance; past performance does not guarantee future results. The investment return and principal value of an investment will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original cost. Current performance of the fund may be lower or higher than the performance quoted. Performance data current to the most recent month end may be obtained by visiting hennessyfunds.com.
- In this article:
- Japan
- Japan Fund
- Japan Small Cap Fund
You might also like
-
 Investment Idea
Why Active Matters When Investing in Japan
Masakazu Takeda, CFA, CMAPortfolio Manager
Angus Lee, CFAPortfolio Manager
Tadahiro Fujimura, CFA, CMAPortfolio Manager
Takenari Okumura, CMAPortfolio ManagerRead the Investment IdeaWhen investing in Japanese businesses, we believe it is imperative to select a manager who is immersed in the culture and can perform in-depth, company specific research to build a concentrated portfolio of Japanese companies that can outperform a benchmark and weather volatility.
-
Fund Commentary
Japan FundA Renewed Focus on Earnings Growth, Shareholder Returns & Valuations
Masakazu Takeda, CFA, CMAPortfolio Manager
Angus Lee, CFAPortfolio ManagerRead the CommentaryThe Tokyo Stock Price Index has risen 25% year-to-date through September and interest rates hit their highest in about 30 years. In this environment, the Portfolio Managers discuss their focus on growth potential and sufficient margin of safety to find companies with different return drivers across different macroeconomic environments.
-
Fund Commentary
Japan Small Cap FundAccess Japan’s Structural Transformation via Japanese Small Caps
Takenari Okumura, CMAPortfolio Manager
Tadahiro Fujimura, CFA, CMAPortfolio ManagerRead the CommentaryIn the following commentary, the Portfolio Managers discuss opportunities in Japan’s small-cap market, highlighting attractive valuations, evolving tourism trends, and earnings growth.
